I. While Europe is still debating "how to make electric heavy-duty trucks a viable proposition," China has already moved on to determining "which use cases are best suited for electrification."
The rapid growth of China's new energy heavy trucks is indeed inseparable from several key factors.
On one hand, the fuel costs of diesel heavy trucks have remained high over the long term.
On the other hand, industrial electricity rates, off-peak electricity, battery swap/charging station operating models, and battery leasing models are continuously lowering both the energy and purchasing thresholds for new energy heavy trucks.
More importantly, China did not push all transportation scenarios toward electrification simultaneously. Instead, it broke through starting with the scenarios where the economics are easiest to calculate:
Port short-haul; mining area transportation; steel plant and power plant shunting; urban muck and construction waste; fixed-route transportation for coal and aggregates; and high-frequency transportation of around 100 to 300 kilometers.
These scenarios share a common characteristic: fixed routes, stable mileage, high vehicle utilization rates, and clearly defined charging/refueling locations.
For a heavy truck operating at high frequency every day, the gap in energy costs is rapidly amplified.
Public cases show that under specific operating conditions and electricity prices, the energy cost per kilometer for battery-electric heavy trucks can be only about half that of diesel heavy trucks.
Once the annual mileage exceeds 100,000 kilometers, the energy savings are sufficient to cover a portion of the purchase price difference.
Therefore, the increase in the penetration rate of new energy heavy trucks in China is not just because of "policy requirements to buy," but more so because in certain scenarios, fleets have realized that not using new energy might actually be more expensive.
 II. The key breakthrough for China's new-energy heavy-duty trucks lies not in the batteries themselves, but in the transformation of energy replenishment into an integral part of the operational process.
Levine noted that electric trucks must "be able to charge, be able to run, and make financial sense."
Among these three aspects, the most difficult part is actually not the battery technology, but the energy replenishment network.
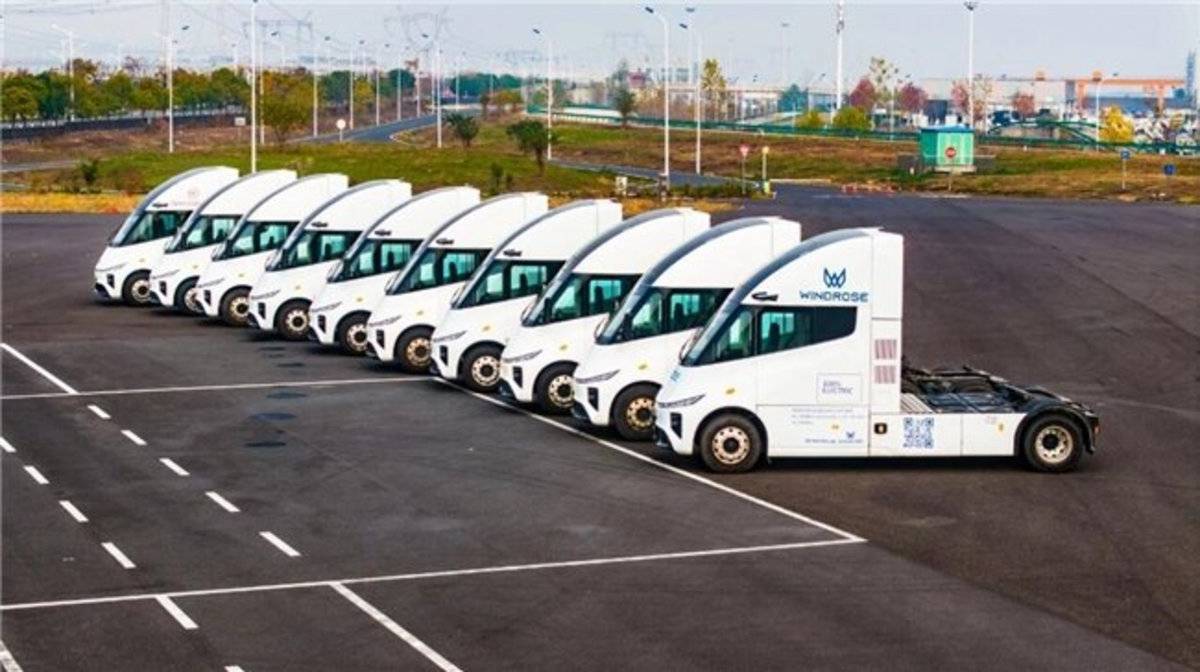
The Chinese market has currently developed two main routes: battery charging and battery swapping.
Charging heavy trucks are more suitable for fleets with fixed parking times. Vehicles return to the depot at night and utilize off-peak electricity to complete charging. The operational logic is quite similar to centralized refueling in traditional fleets.
Battery-swapping heavy trucks, on the other hand, are more suitable for continuous operation scenarios such as mining areas, ports, and steel plants. Completing a battery swap in just a few minutes can reduce vehicle waiting time and improve vehicle utilization rates.
Battery leasing can also lower the upfront purchase cost, transforming the "buying a truck plus buying a battery" model into a "separation of vehicle and battery" (BaaS - Battery-as-a-Service) model.
III. The issue of payload also exists in China, though it is partially mitigated by differences in operational scenarios.
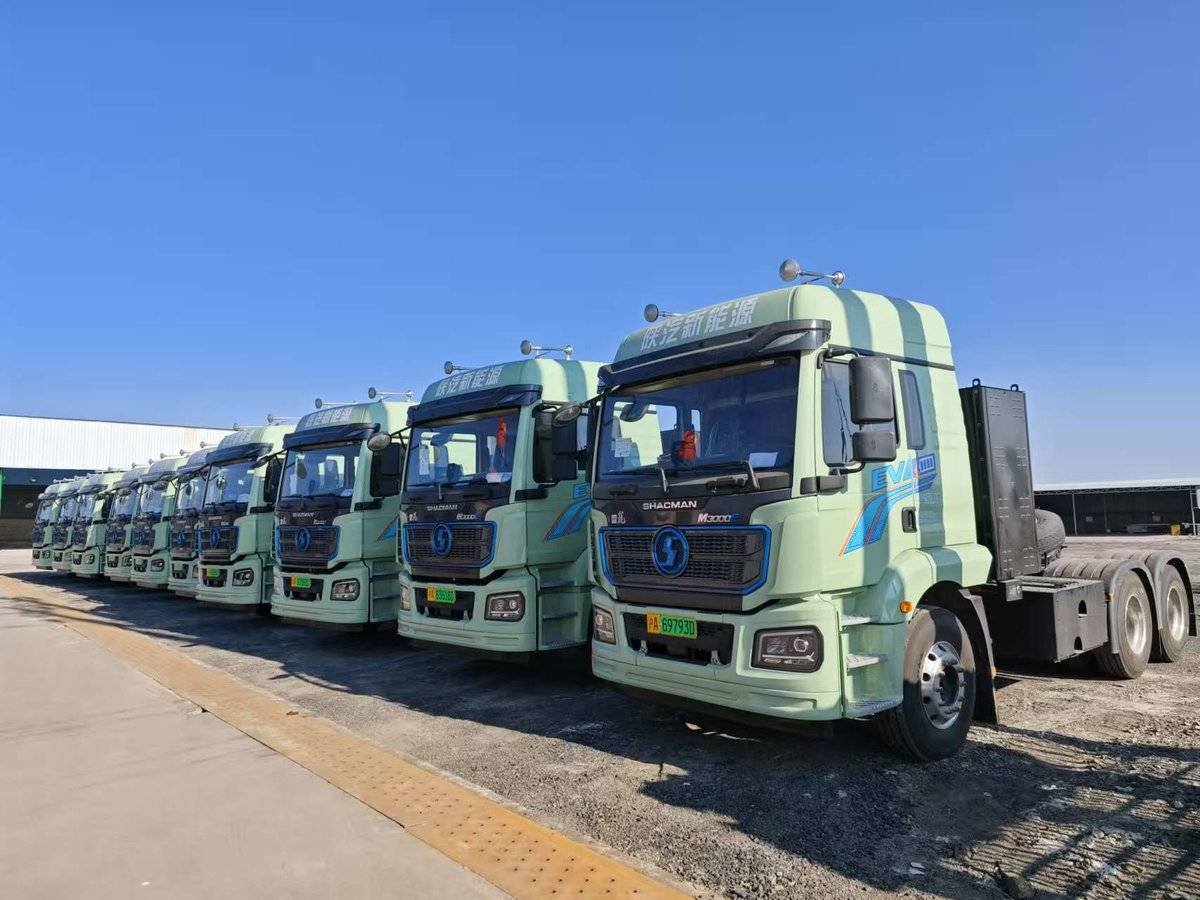
Levine mentioned that the weight of the batteries could cause electric trucks to lose 2 to 5 tons of payload, making it necessary to adjust weight regulations to compensate.
This is not a problem unique to Europe; Chinese new energy heavy trucks also face the issue of added battery weight.
For long-haul trunk line vehicles that are priced by tonnage and operate at full load, carrying a few tons less cargo can directly impact revenue.
Even if new energy vehicles have lower energy costs, if the payload loss is significant and freight rates are lo